Soundings · Issue 04
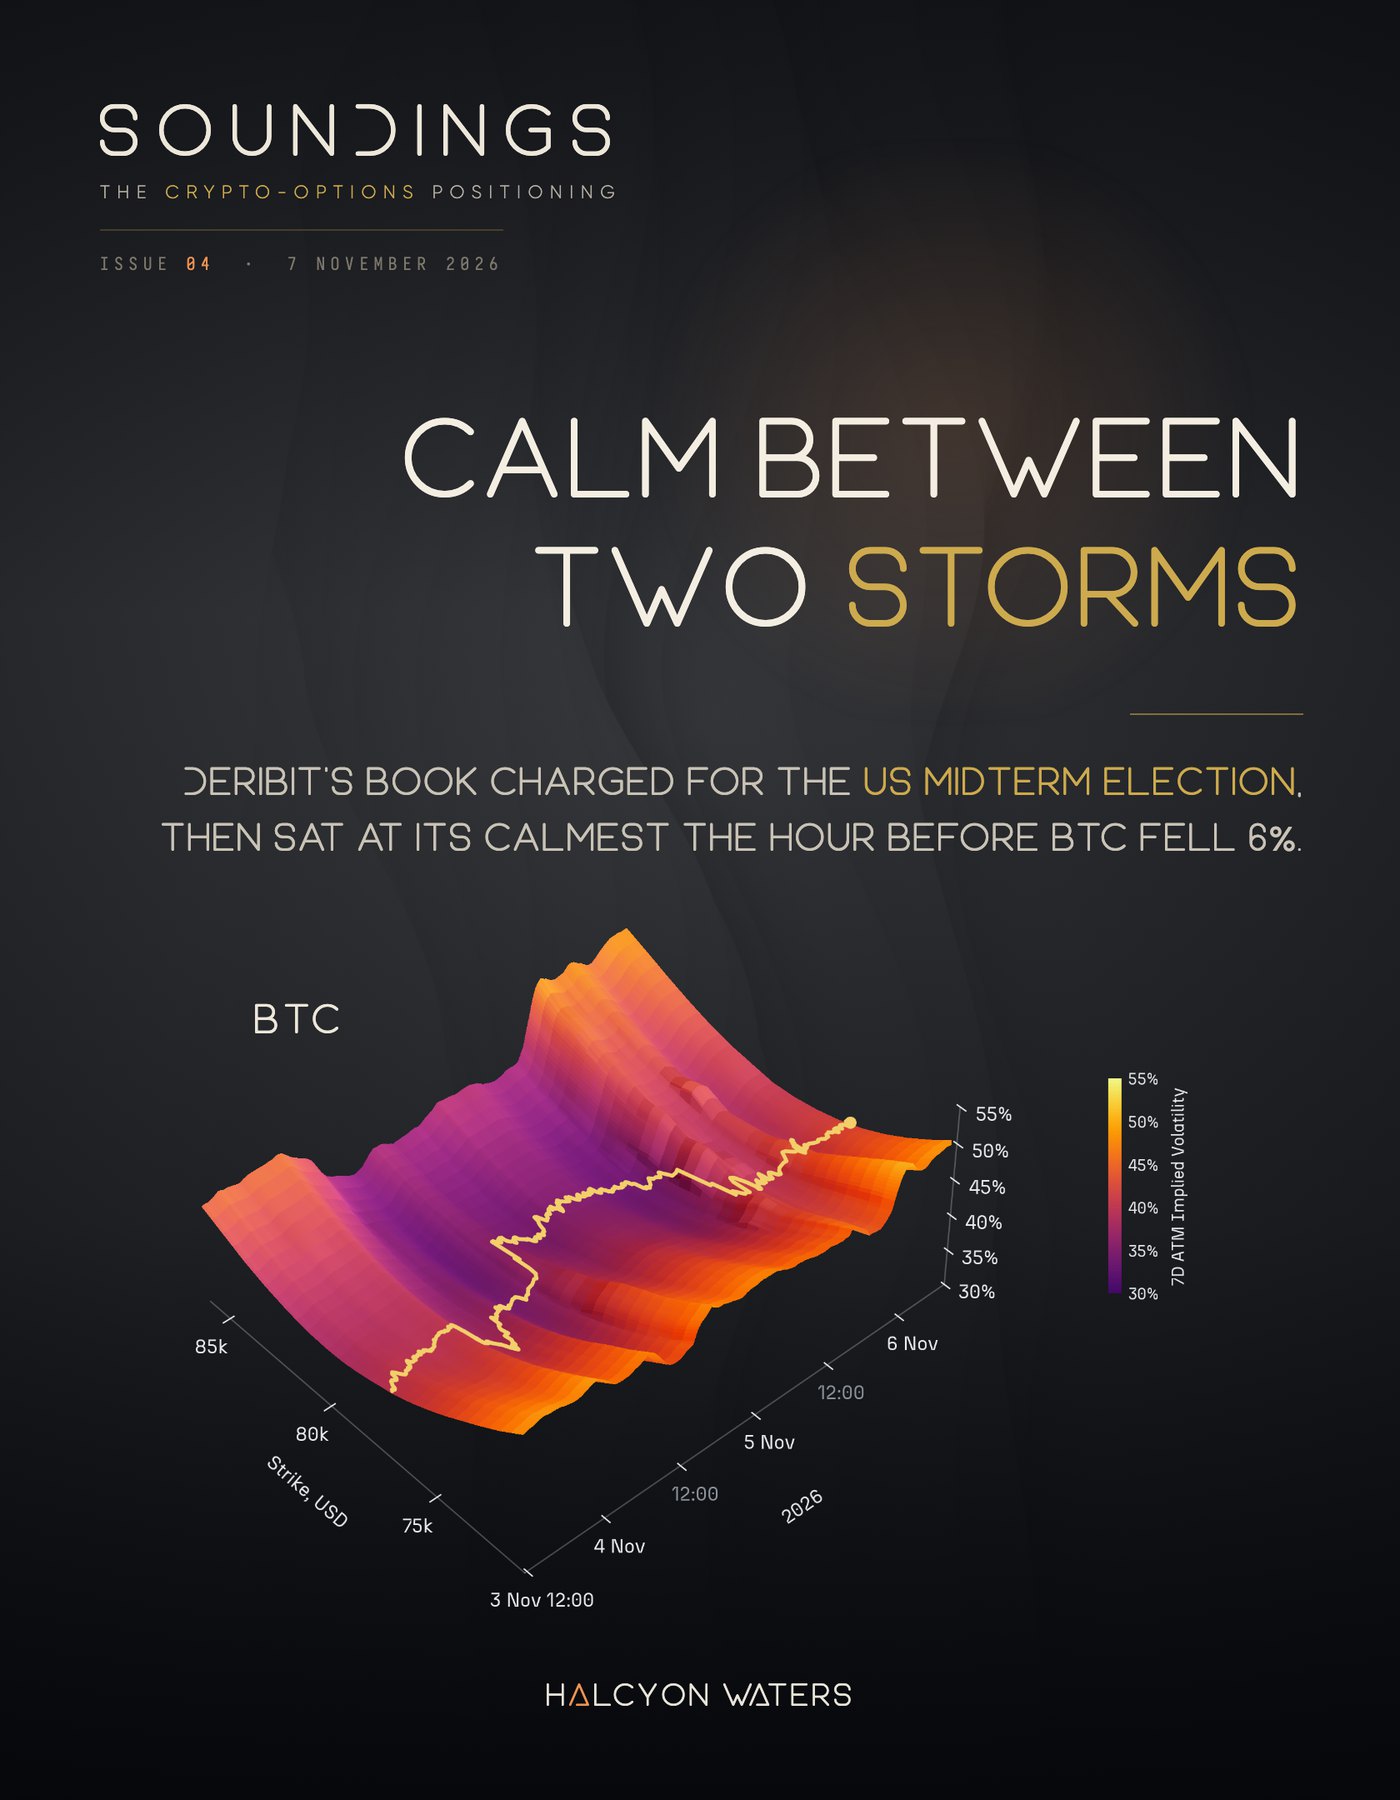
Soundings Issue 04: Calm Between Two Storms
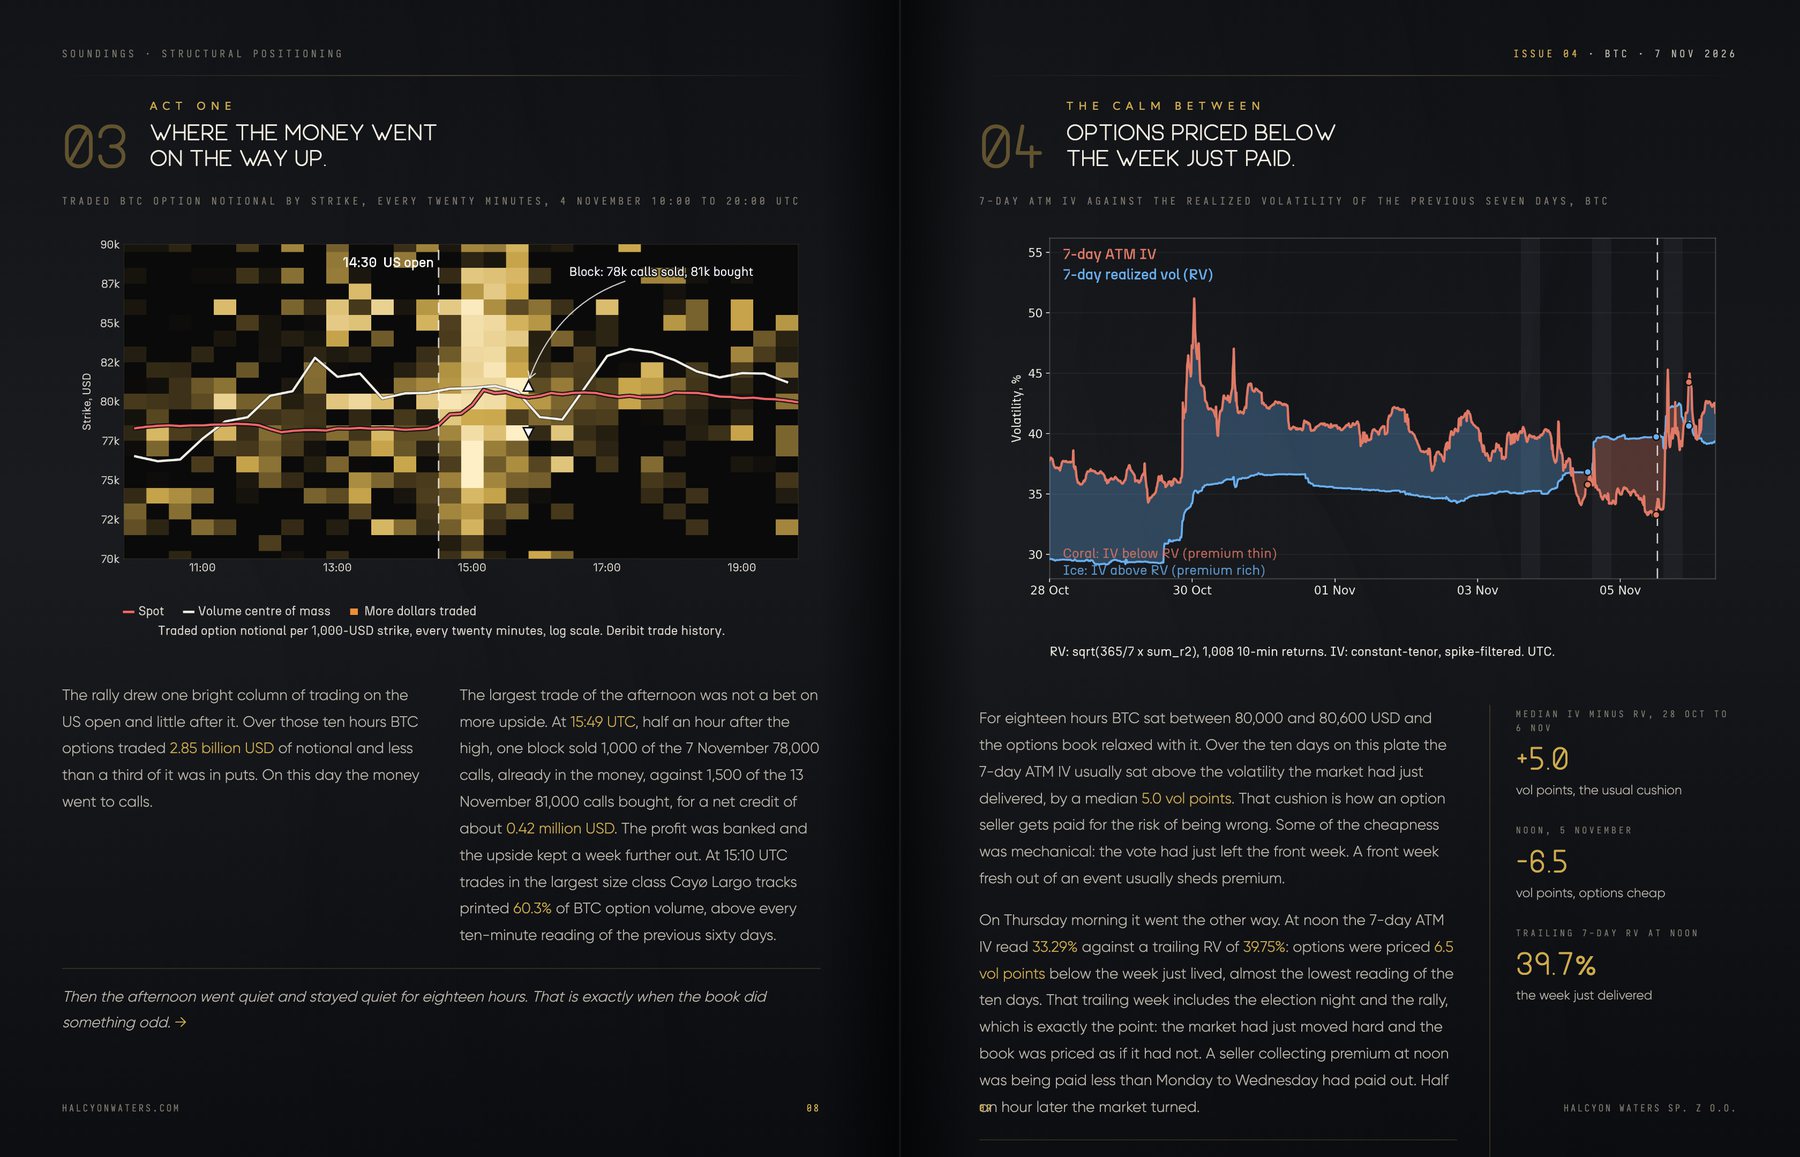
Deribit's BTC options book charged for the US midterm election, let the premium go before the rally and sat at its calmest just before the sell-off of 5 November 2026. Soundings Issue 04 reads the book every ten minutes through both storms.
Every figure here is computed on Cayø Largo, our own crypto-options archive: six coins, every 10 minutes since 2025.
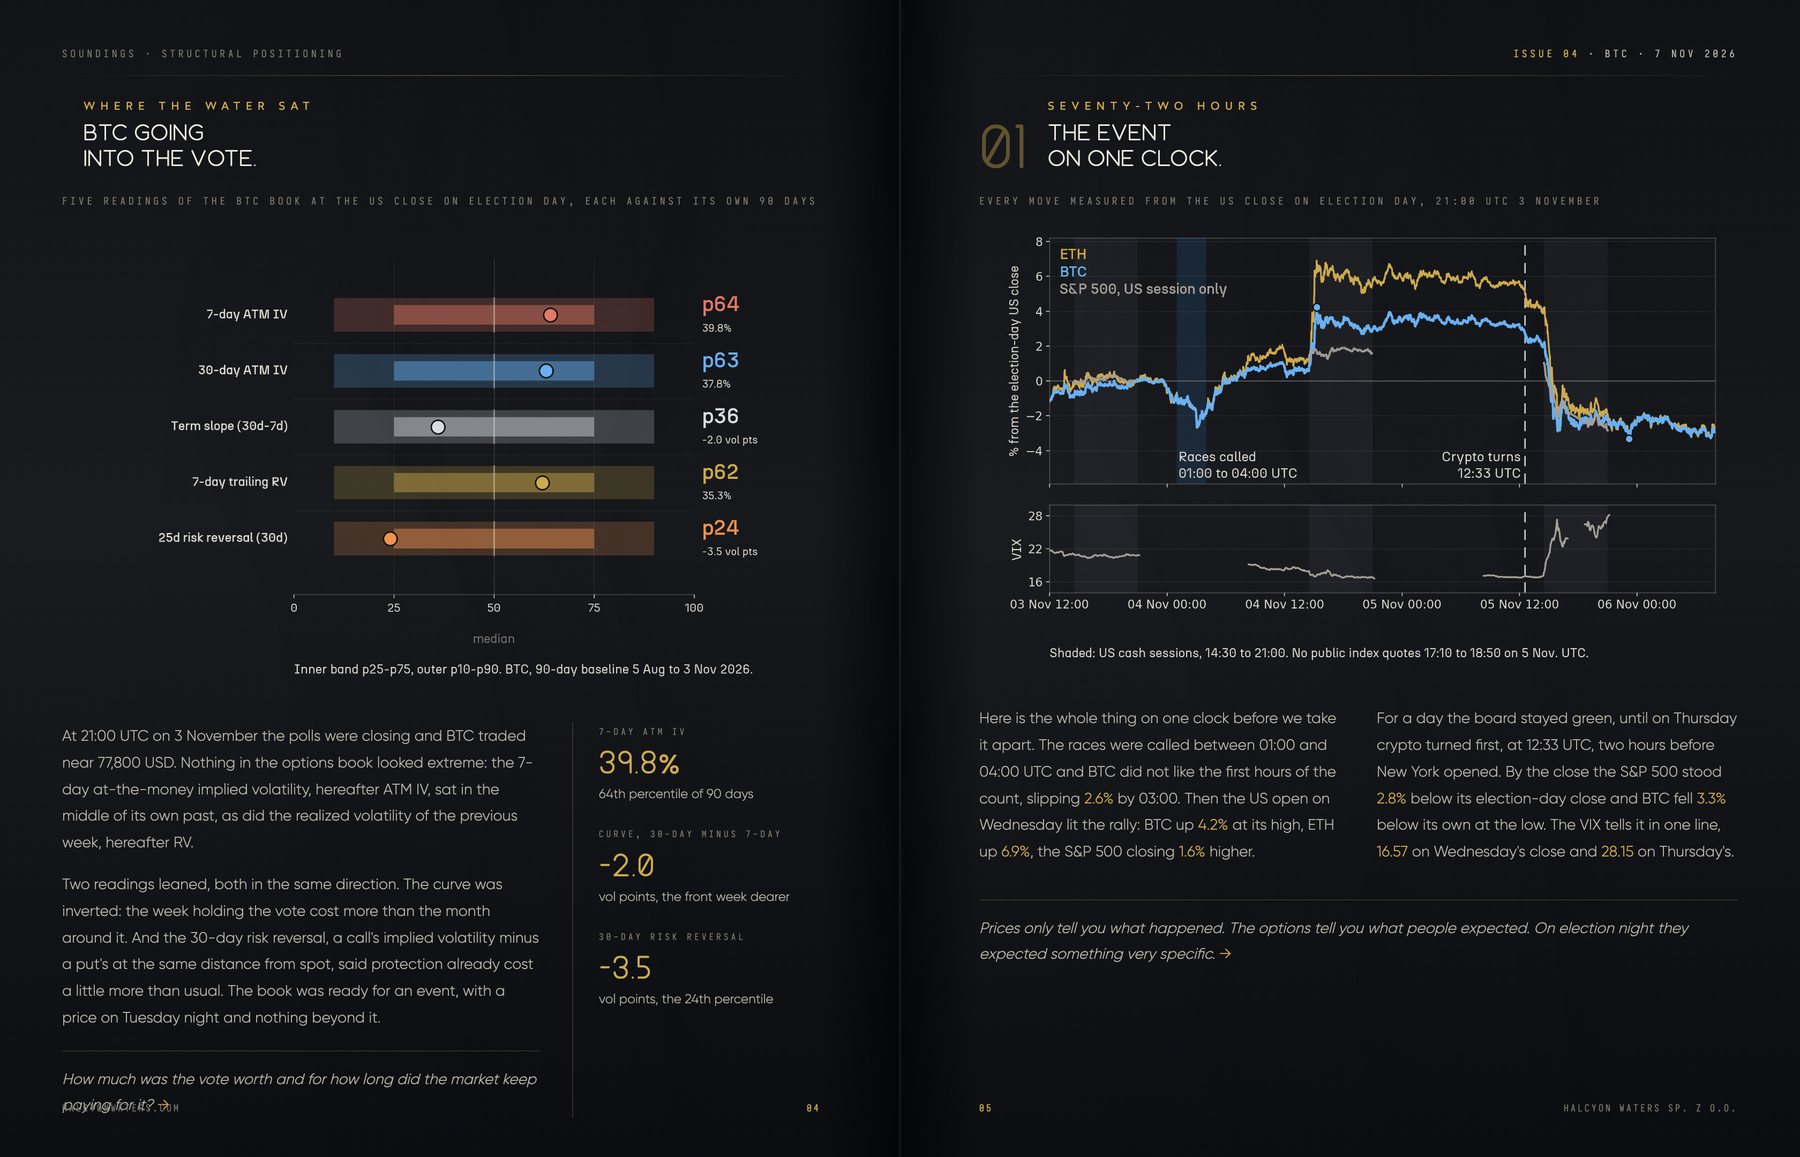
The US voted on Tuesday and BTC rallied on Wednesday. On Thursday it gave all of it back and more, while the S&P 500 had its worst day since April 2025. Two storms in three days, with eighteen hours of calm between them.
Issue 04 reads Deribit's BTC options book every ten minutes through all of it: what the book charged for the vote, how fast it let the premium go, how cheap and calm it was when the second storm arrived, and who was standing where when it did.
What's inside Issue 04
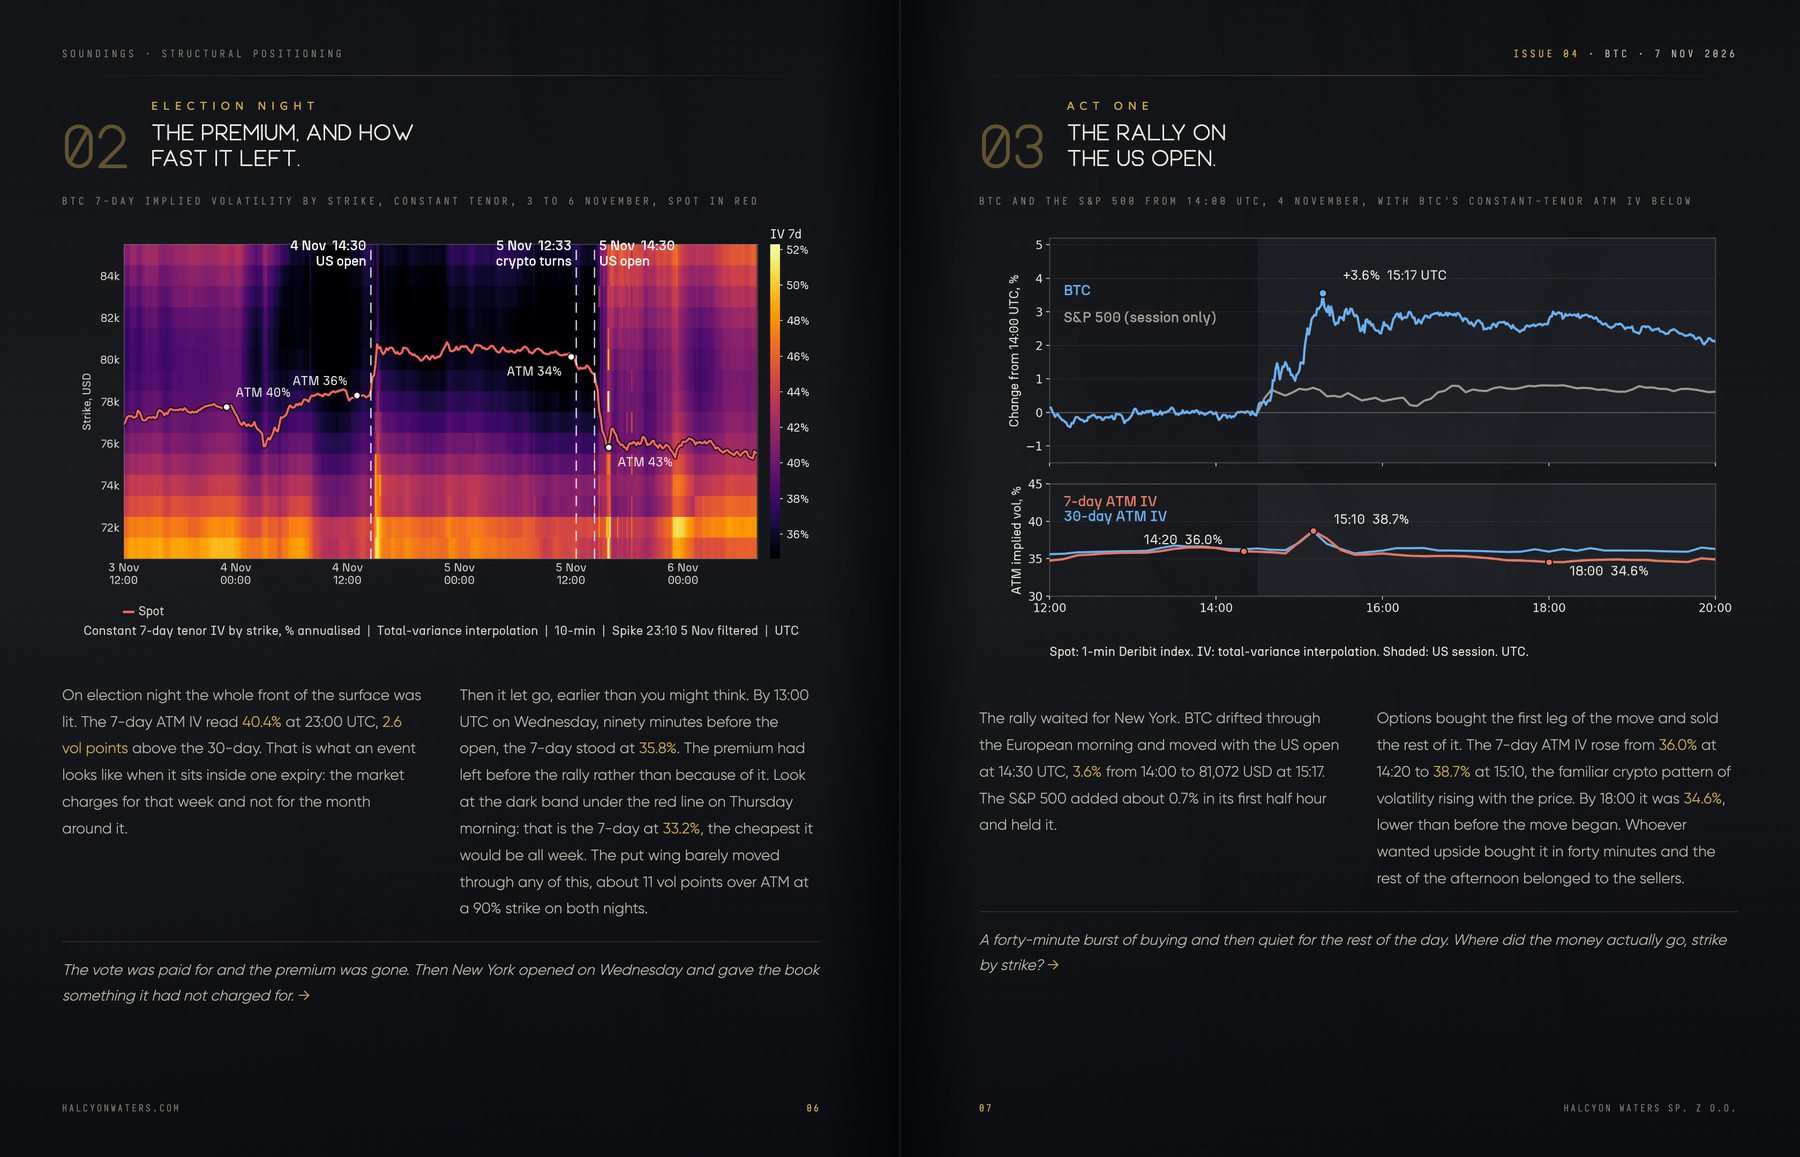
| • | Election night. What the BTC options book charged for the vote and how fast it let the premium go, read off the volatility landscape. |
| • | Act one. The rally on the US open, the forty minutes of buying and the roll at the top. |
| • | The calm between. Options priced below the week just delivered and the flattest skew of the event, before crypto turned. |
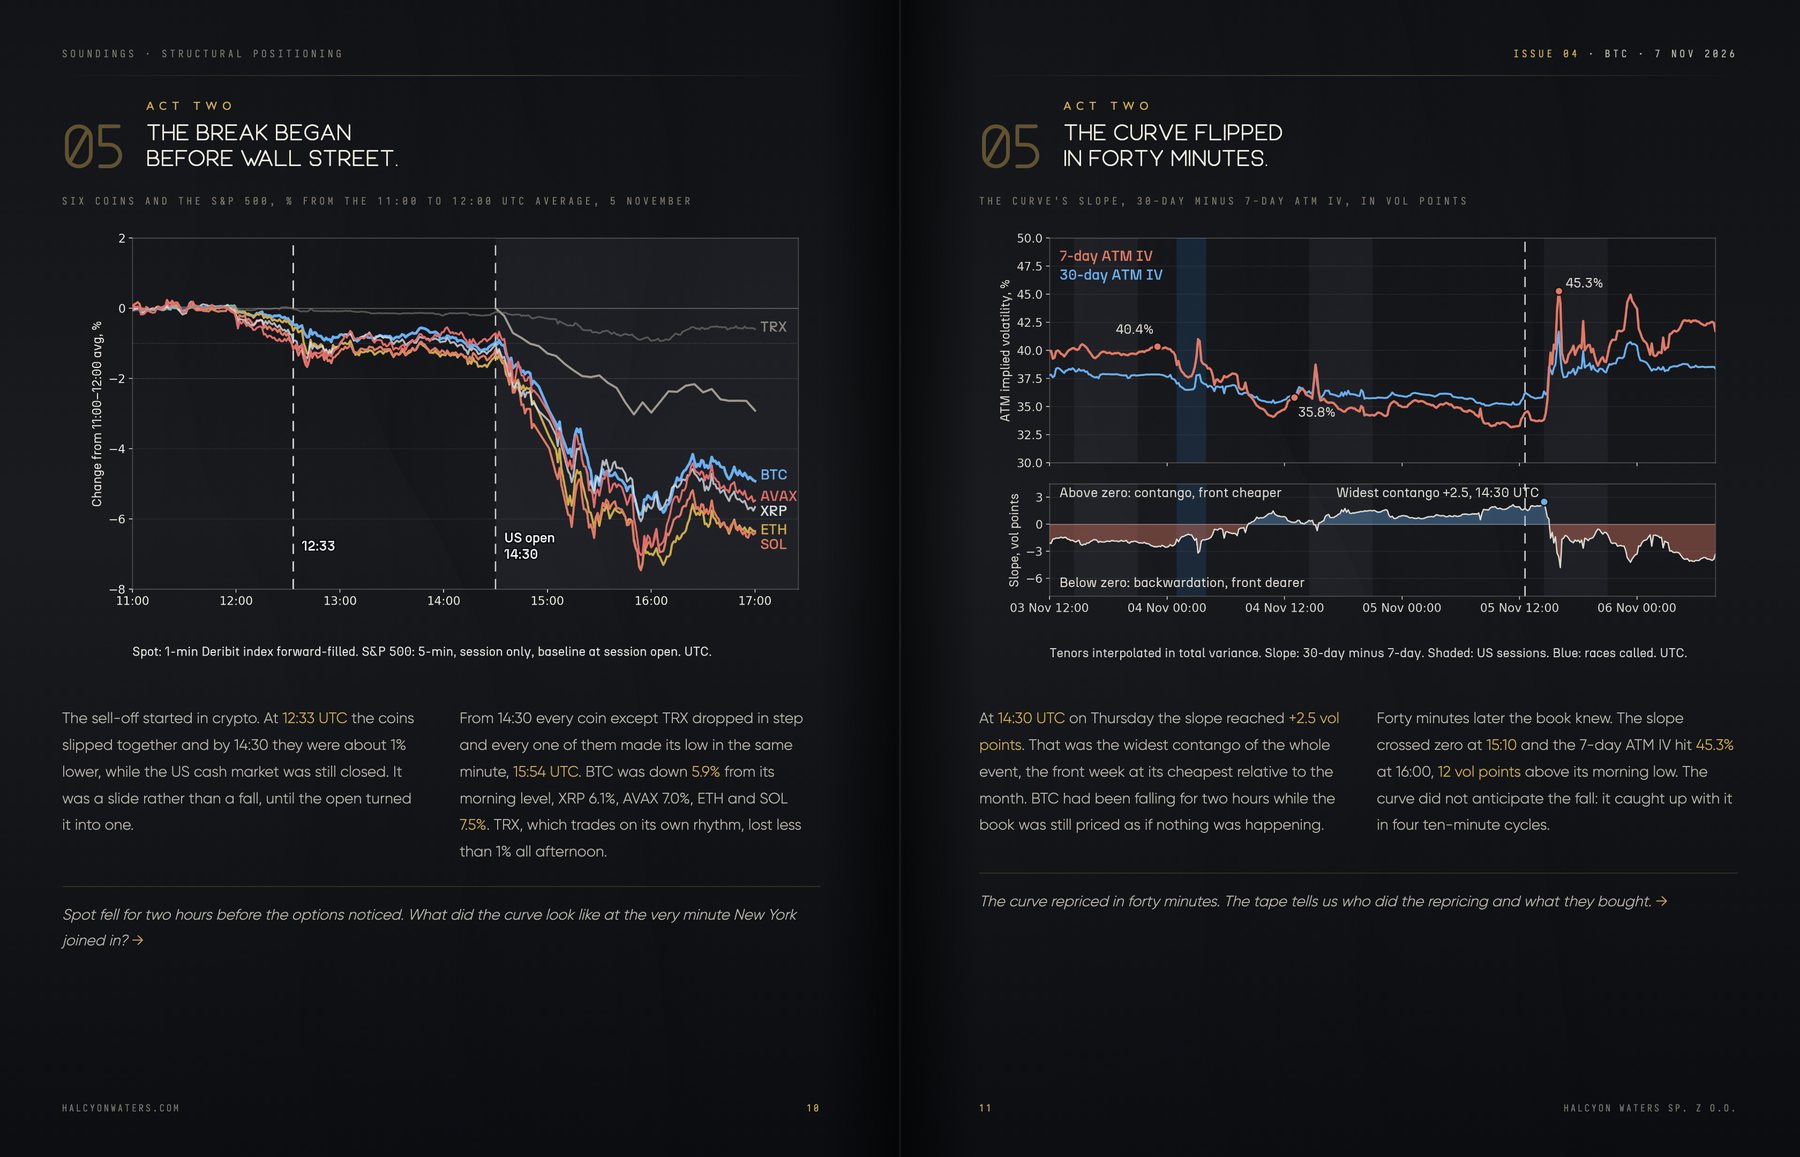
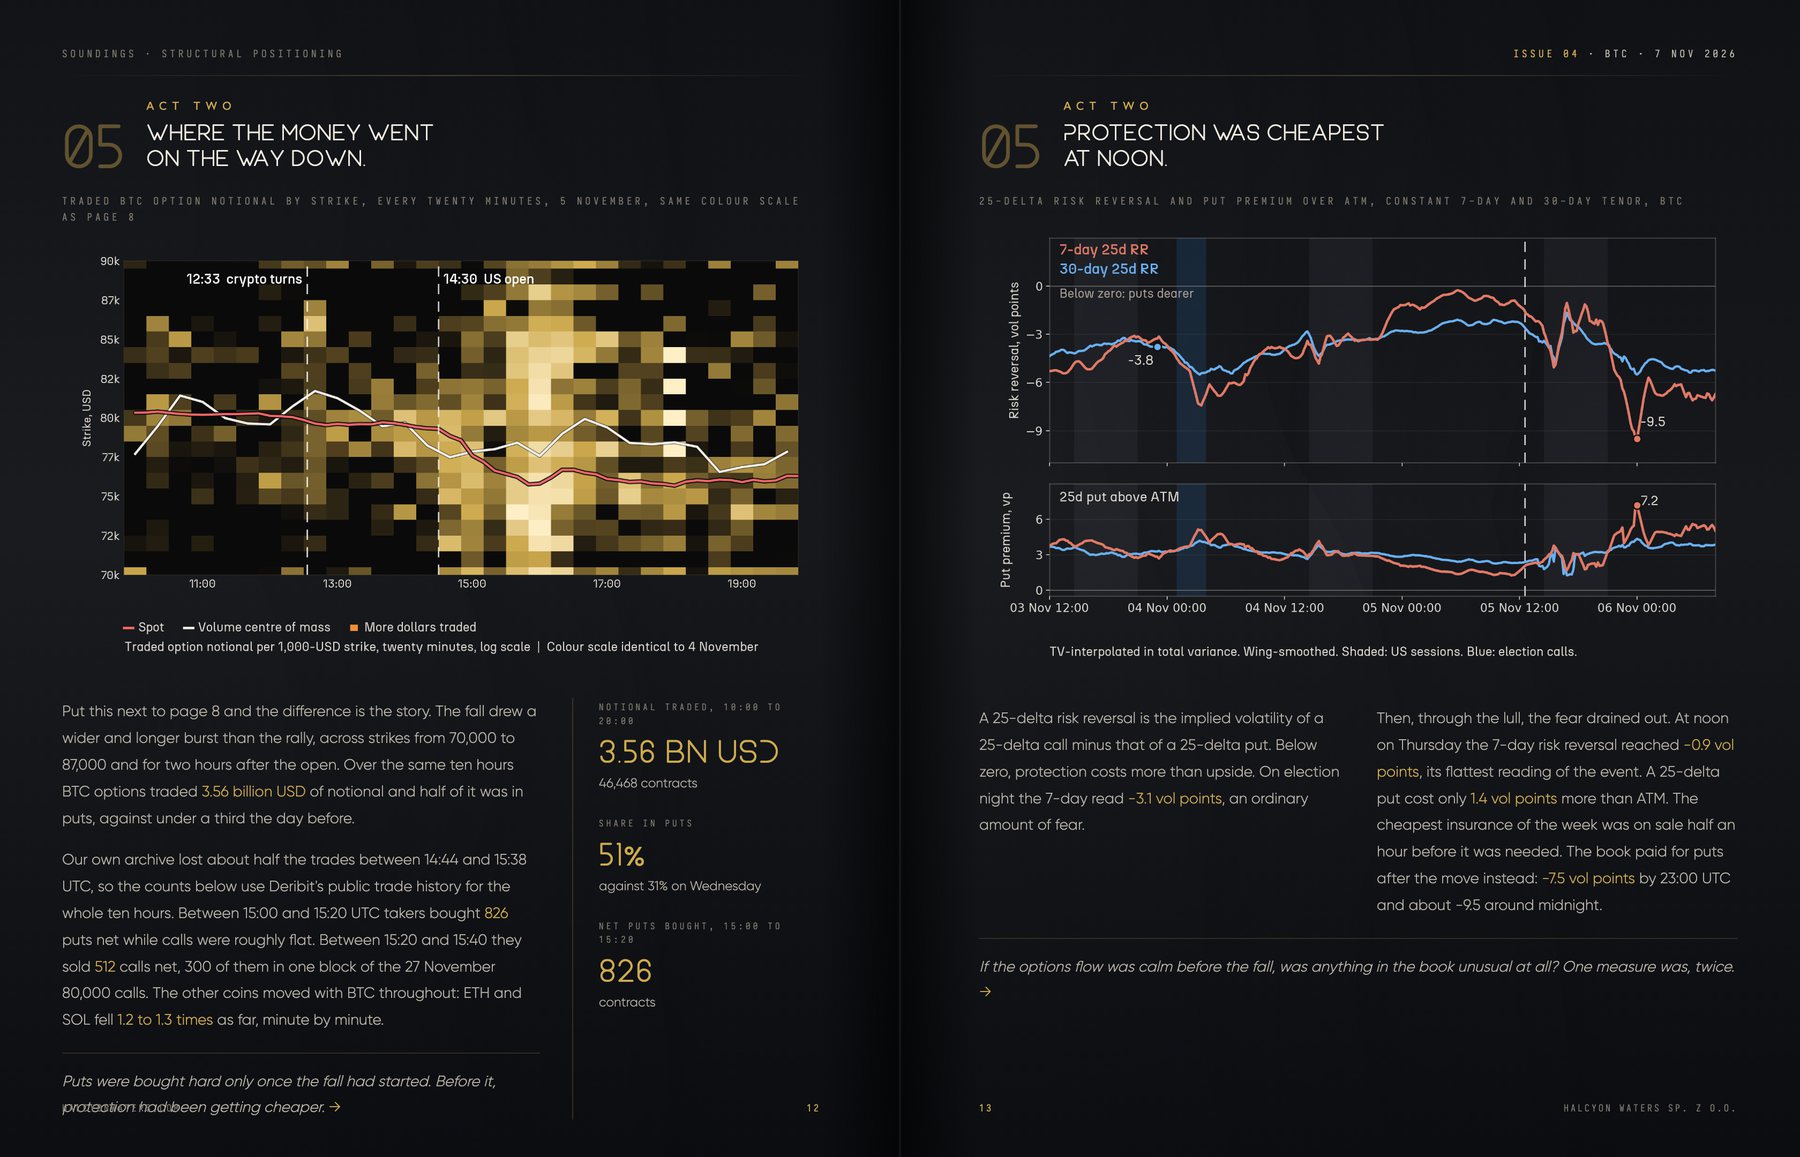
| • | Act two. Crypto turning two hours before Wall Street, the curve flipping in forty minutes and where the money went, strike by strike, as in options thermography. |
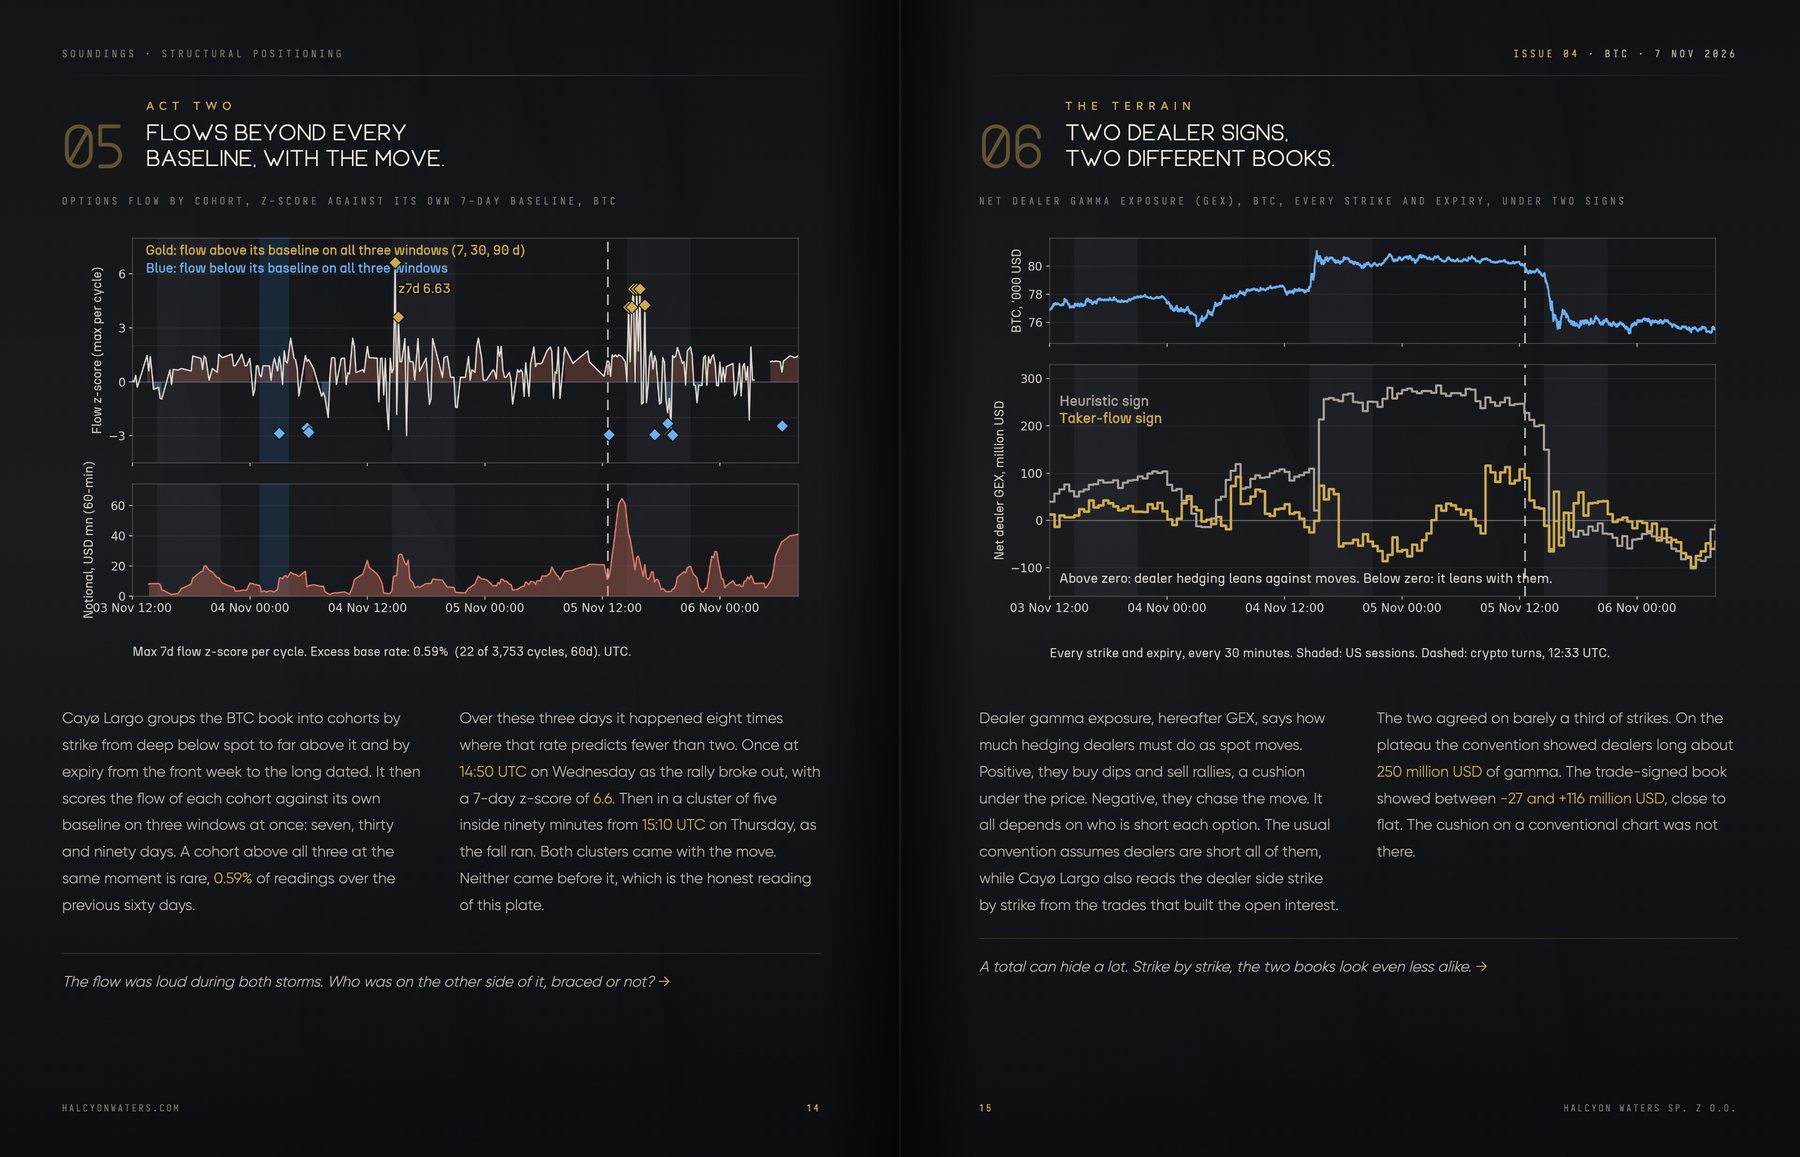
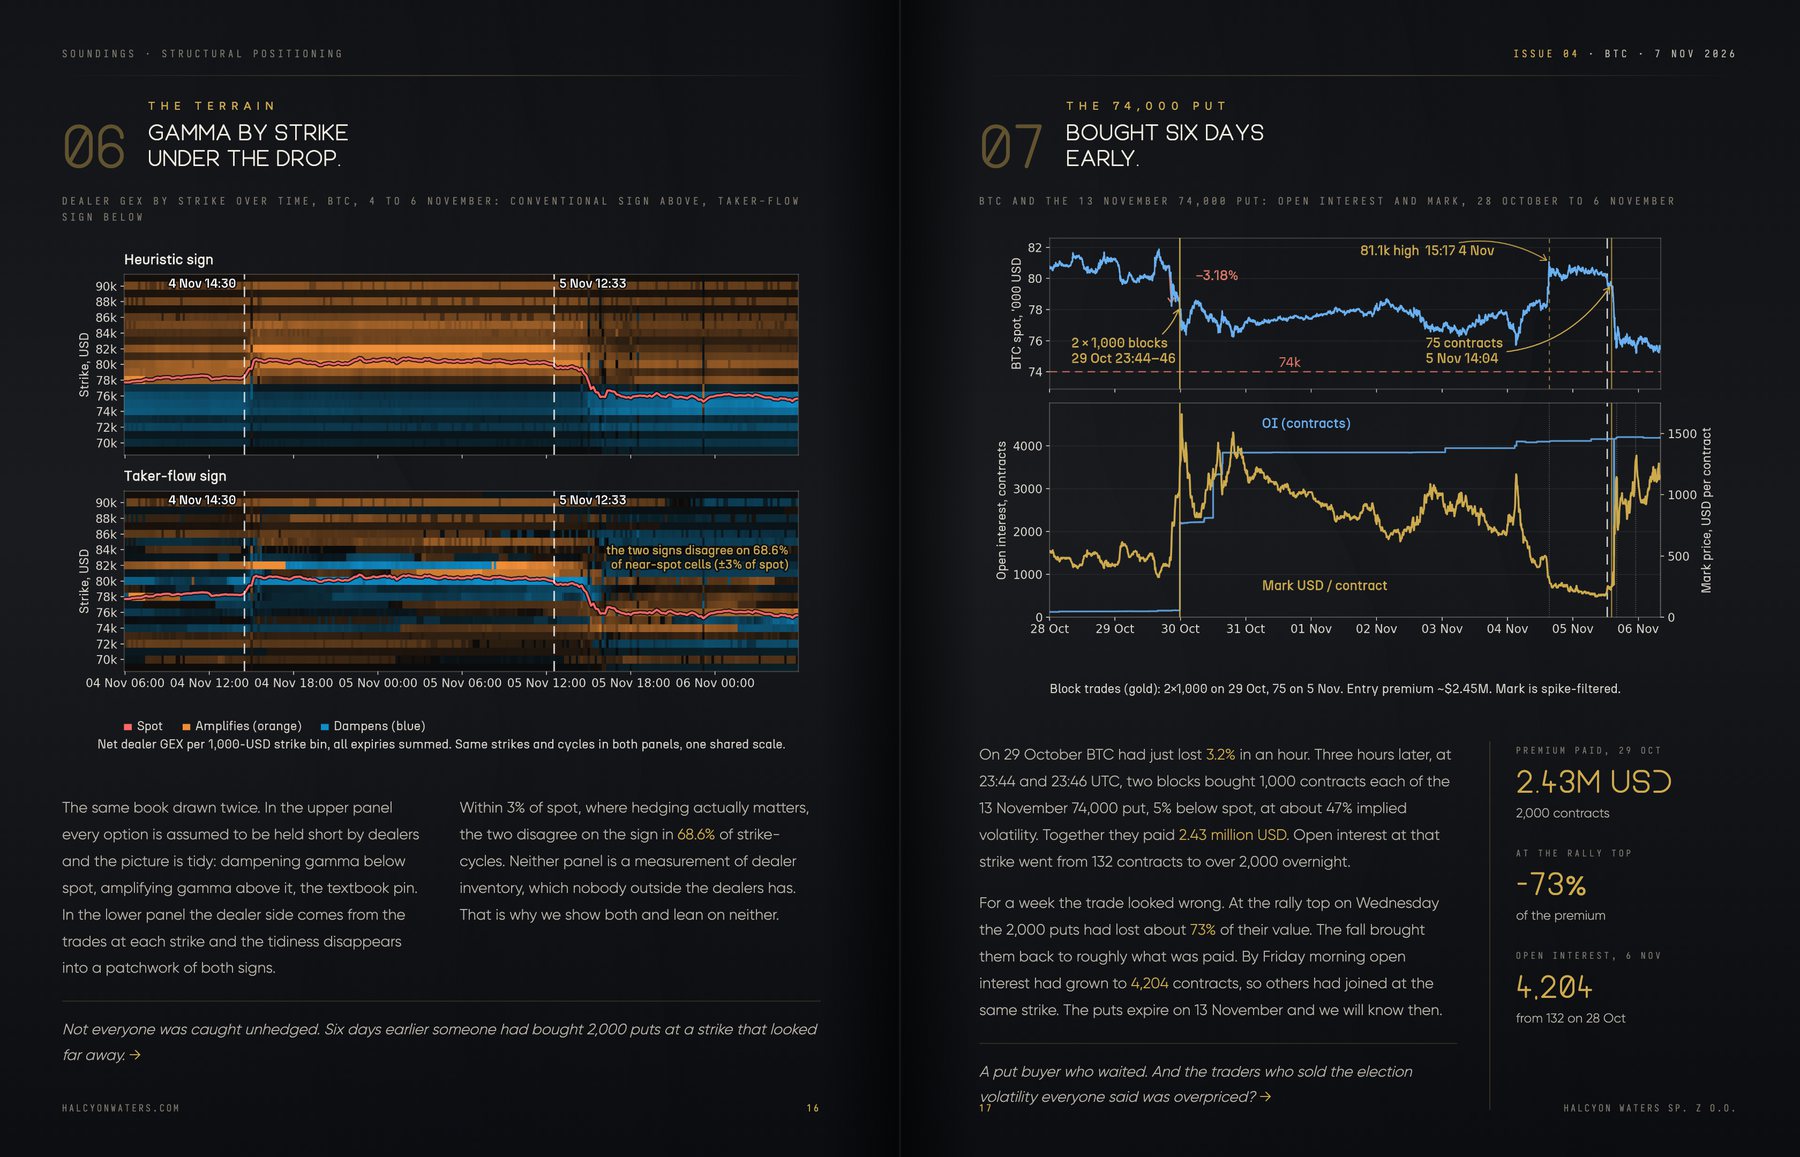
| • | The terrain. Two conventions for dealer gamma and why they disagree near spot, against the GEX landscape. |
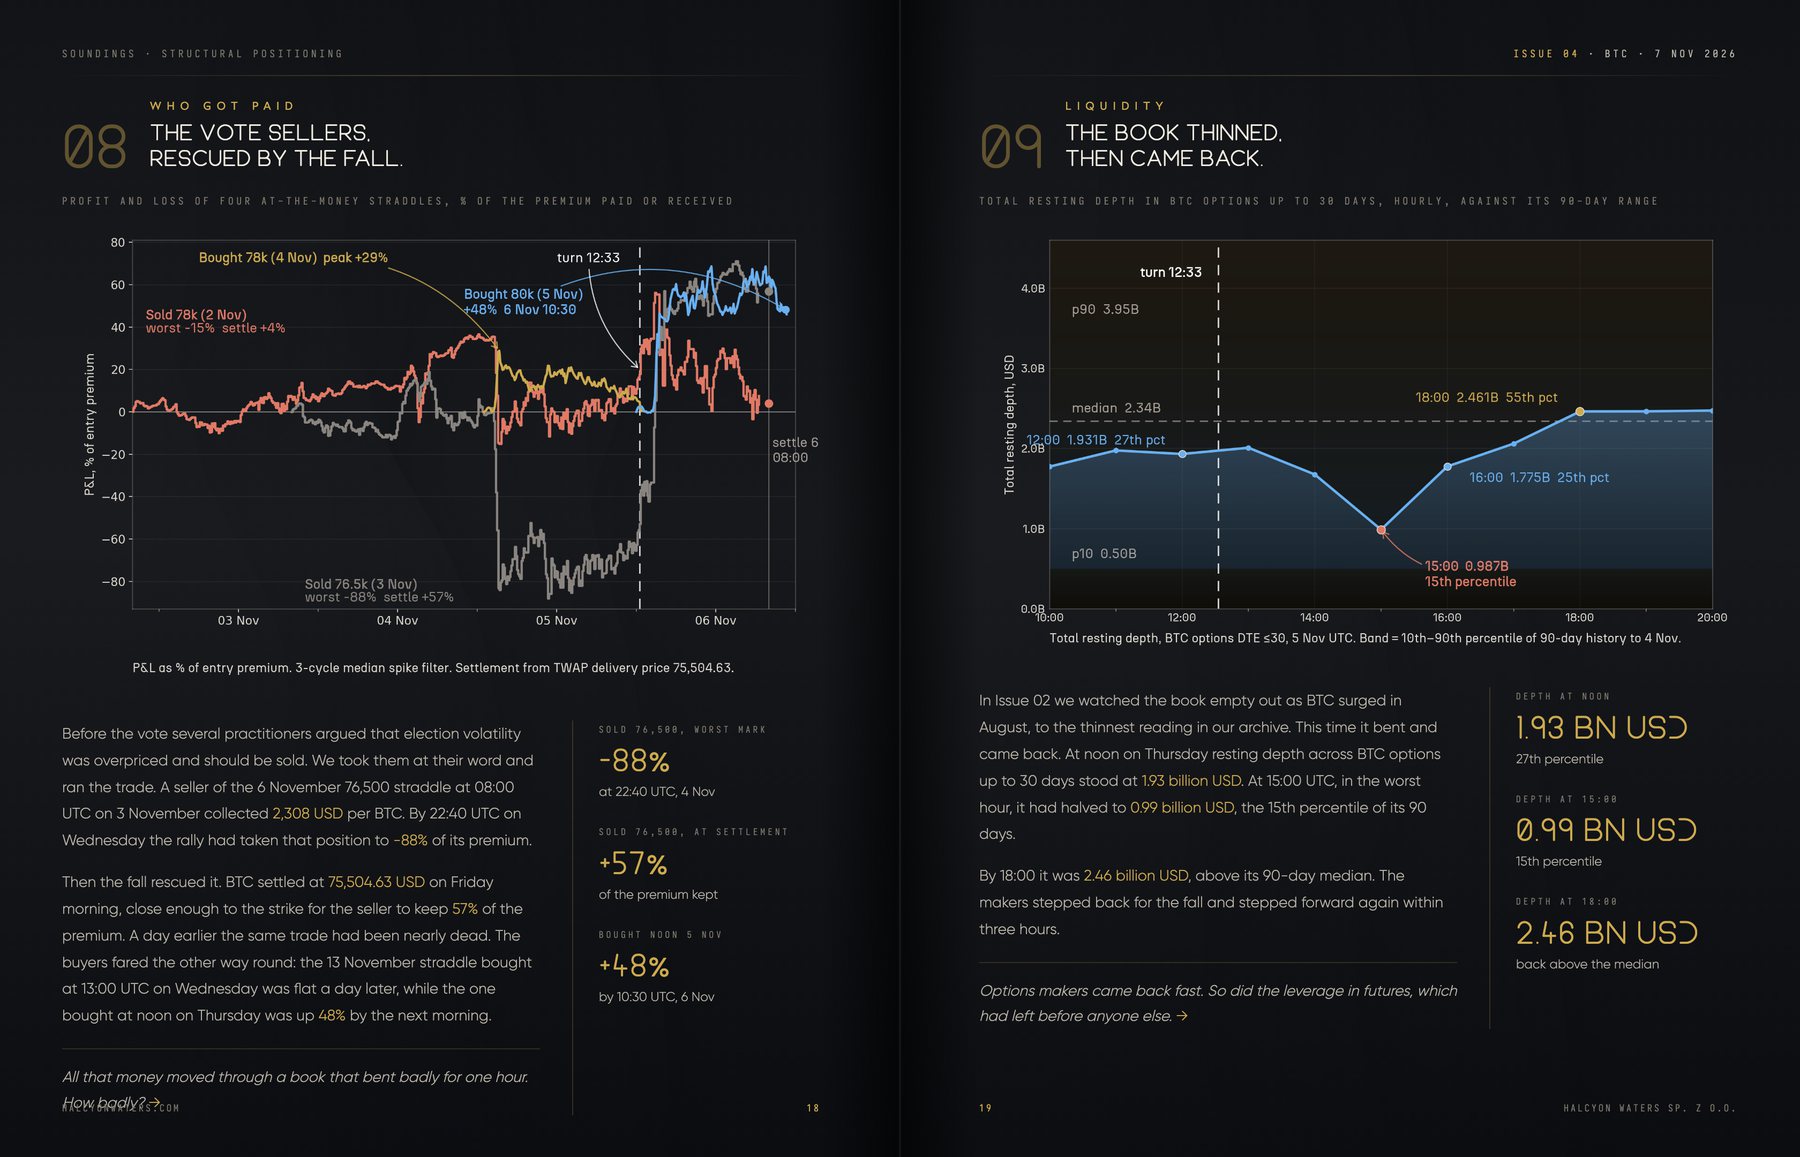
| • | Who got paid. A put bought six days early and the sellers of election volatility, nearly wiped out and then rescued. |
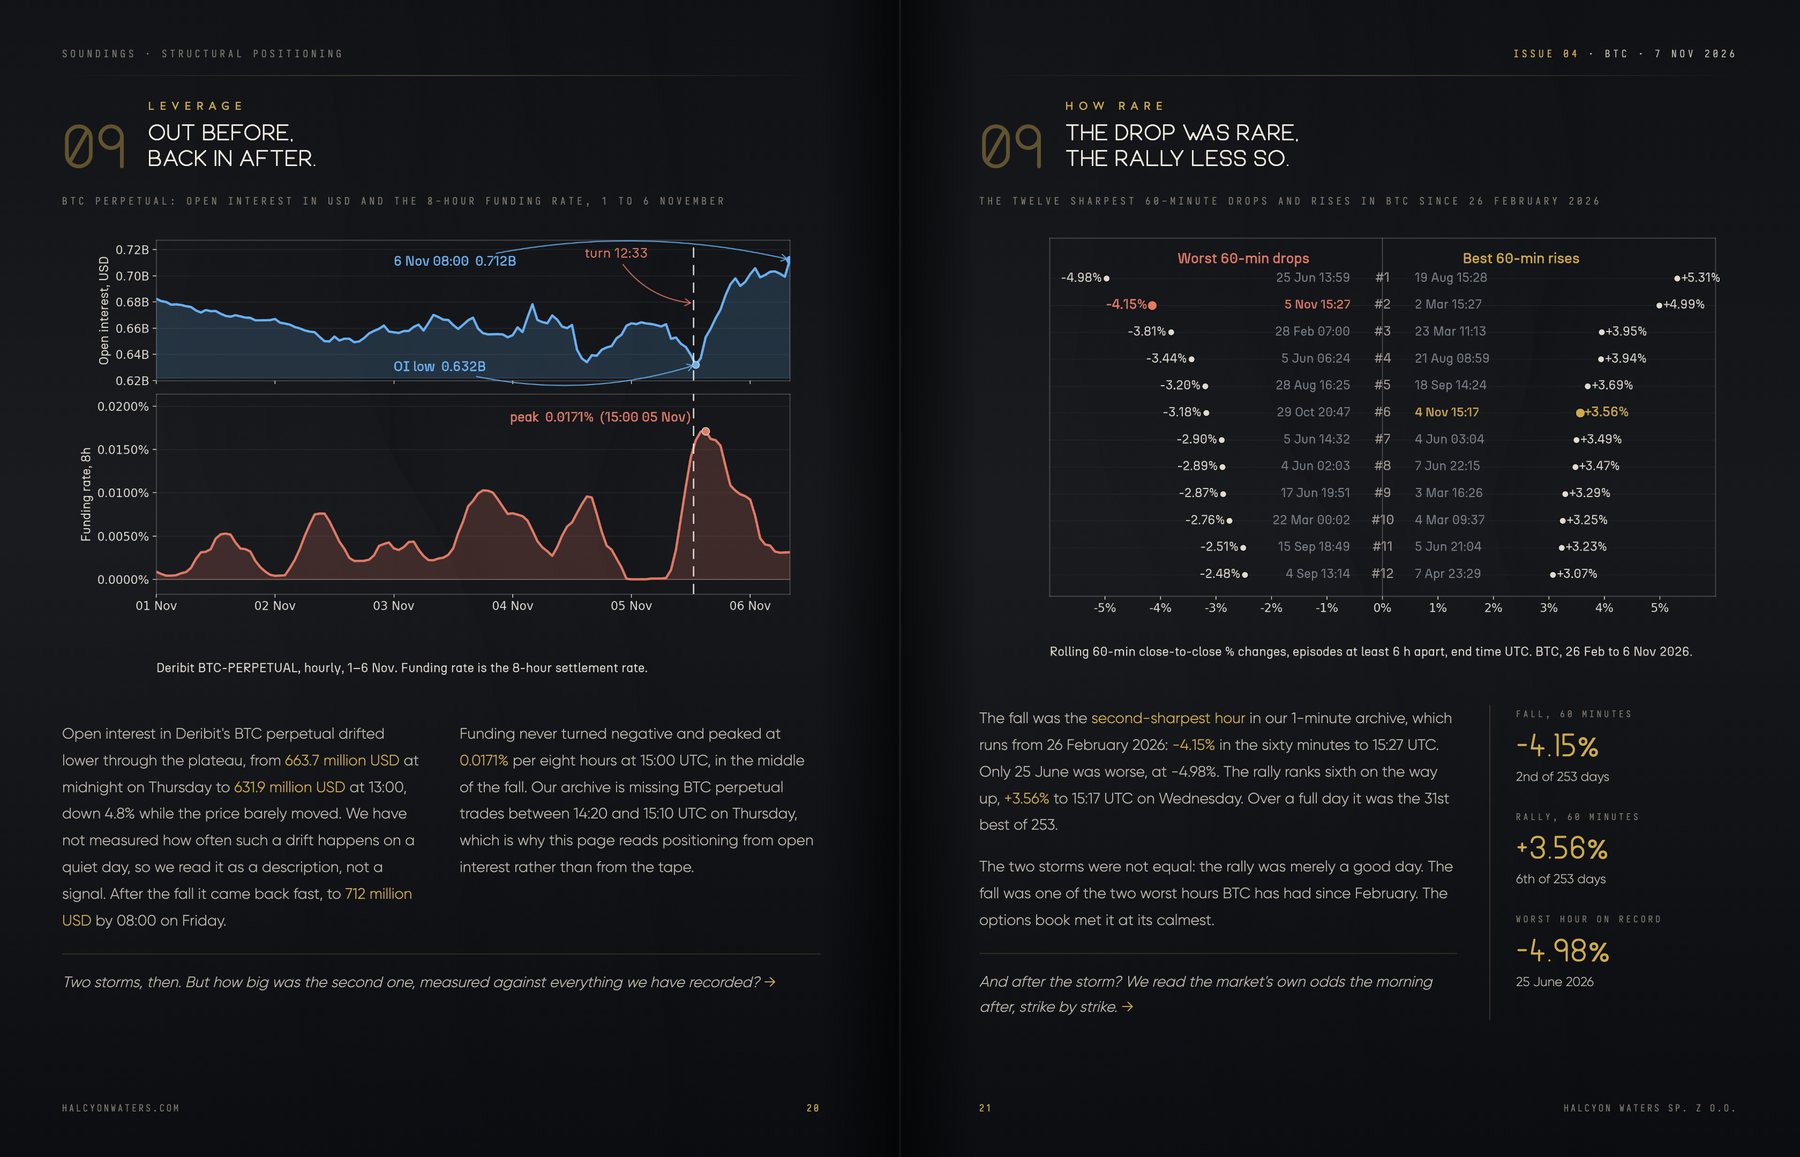
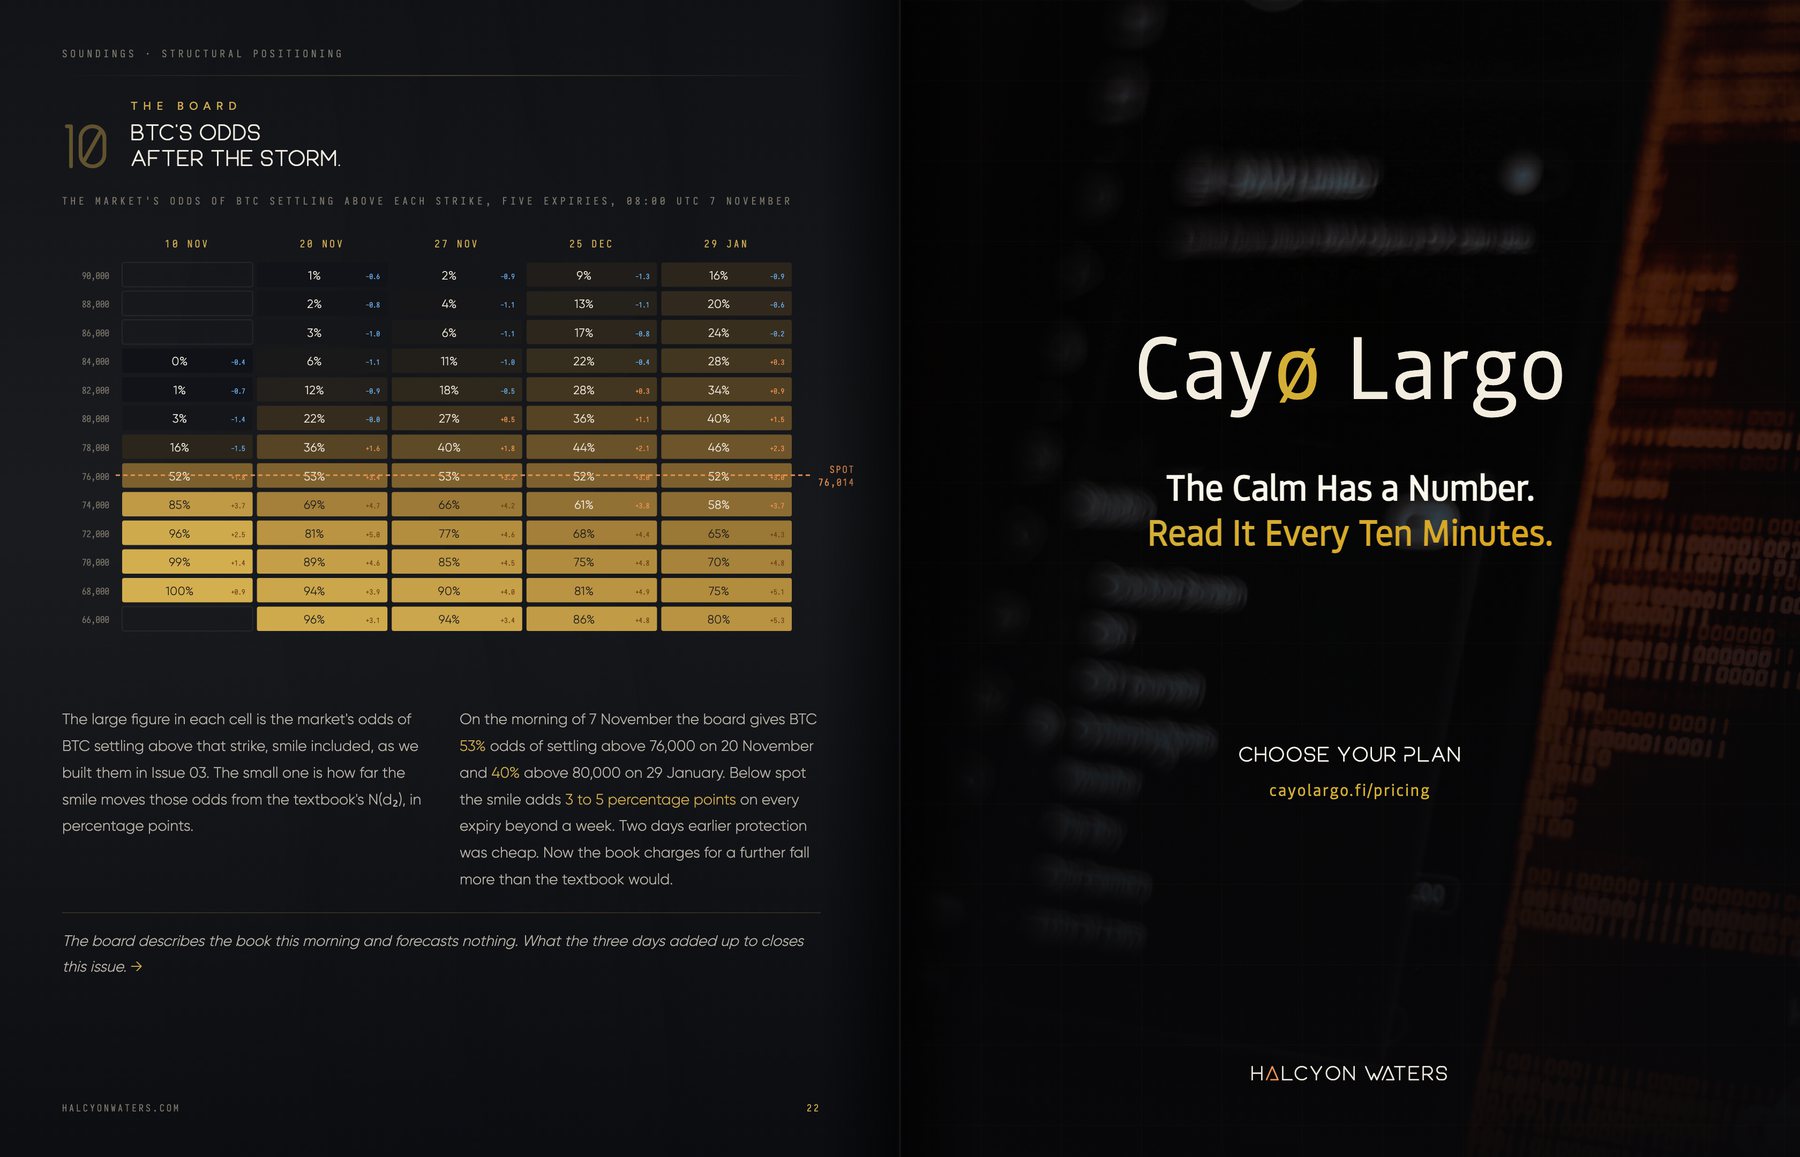
| • | After the storm. Liquidity, leverage, how rare the fall was and the market's odds at every strike on 7 November. |
Frequently asked questions
What does Soundings Issue 04 examine? How Deribit's BTC options book read the US midterm election of 3 November 2026, the rally on the US open of 4 November and the cross-asset sell-off of 5 November, when the S&P 500 fell 4.36% and BTC had its second-sharpest hour since February 2026. The book is read every ten minutes through all three days.
What was the main finding? The book priced the vote in the front week and let that premium go before the rally. By late Thursday morning, before crypto turned at 12:33 UTC, BTC's 7-day at-the-money implied volatility was the cheapest of the week and 6.5 vol points below the realized volatility of the previous seven days, with the flattest skew of the event. The book repriced after the fall rather than before it.
Did anything in the options book warn of the sell-off? No. Issue 04 looked at the implied level, the term structure, the skew, the premium over realized volatility, cohort flows and large-lot taker flow. The only reading that turned bearish beforehand, large-lot flow at noon, had fired 568 times in the archive and preceded a 2% drop within three hours only ten times.
What does the issue show about dealer gamma? On the plateau between the two storms the usual convention, which assumes dealers are short every option, showed dealers long about 250 million USD of gamma. Reading the dealer side strike by strike from the trades showed a book close to flat. Within 3% of spot the two conventions disagreed on the sign in 68.6% of strike-cycles.
Is Soundings investment advice? No. Soundings describes the structure of the crypto options book. It contains no price or volatility forecast and no recommendation to buy, sell or hold any instrument. It is published by Halcyon Waters sp. z o.o. using Deribit data.
The next issue, in your inbox
Soundings reads where the crypto-options book is positioned. It never forecasts price.
Soundings. Once a month. In your mailbox.